
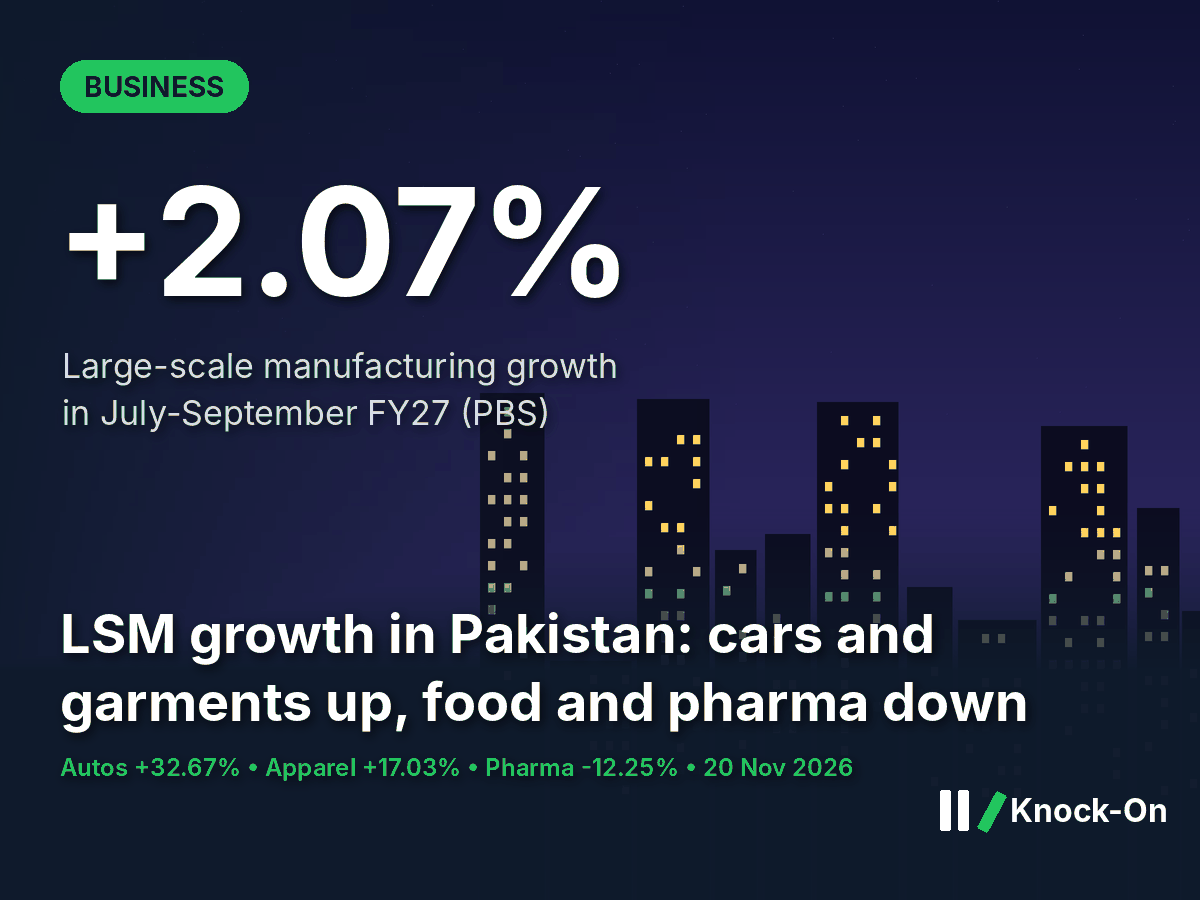
LSM growth in Pakistan was 2.07% in the first quarter of FY27, Pakistan Bureau of Statistics (PBS) data released on Thursday show. That is positive but uneven: large-scale manufacturing is being carried by cars, garments and fuel, while food, medicines, chemicals and steel, which together touch almost every household and factory, are making less than a year ago.
The short version
- Large-scale manufacturing (LSM) grew 2.07% in July-September FY27, below the 4.98% recorded for FY26 as a whole.
- September alone was up 2.45% year on year and 3.18% on August.
- 12 of 22 sectors grew; autos (+32.67%) and apparel (+17.03%) led, while pharmaceuticals (-12.25%) and iron and steel (-11.77%) fell most.
- The PSX rose 0.27% on Thursday, with analysts citing value buying and improving industrial activity.
What happened
According to PBS figures reported by Dawn, the Quantum Index of Manufacturing stood at 116.79 in September, against 114.00 a year earlier. Monthly growth was choppy: 3.03% year on year in July, 0.65% in August and 2.45% in September. Knock-On covered the weak August reading in our earlier report on LSM growth.
Apparel added 2.91 percentage points to quarterly growth, autos 1.26 points and petroleum products 0.98 points. Food took away 1.26 points, chemicals 0.77, textiles 0.72, pharmaceuticals 0.71 and iron and steel 0.49.
Cars and garments are growing fast; staples and inputs are shrinking
LSM growth by sector, July-September FY27 vs a year earlier, %
Why it matters
Factory output is the clearest real-time gauge of whether the economy is reaching the SBP’s FY27 growth range of 3.5-4.5%, discussed in our report on the SBP GDP growth forecast. Quarterly LSM growth of 2.07% is well short of last year’s 4.98% pace. The mix matters too: autos growth has slowed sharply from last year’s 84.61% first-quarter surge, and textiles, with an 18.16% weight in the index, fell 5.95% in September.
The knock-on effects
First order: LSM growth Pakistan depends on a few sectors
Apparel alone added more than the whole index grew. Garment exporters and carmakers are hiring and buying inputs; food processors, drugmakers and steel mills are running below last year.
Second order: suppliers and lenders feel the split
Auto-parts makers, packaging firms and banks lending to carmakers benefit, while suppliers to steel and pharma face slower orders. Weaker spinning and weaving alongside strong garment output points to more value being added at the end of the chain.
Third order: markets and policy
The KSE-100 rose 477.86 points to 176,772.19 on Thursday, ending two losing sessions after Wednesday’s fall on Gulf risks, with analysts citing value buying and improving industrial activity. A sustained recovery in industry would ease pressure for further policy support.
Who could benefit
- Garment exporters: output up 17.03% in the quarter.
- Carmakers and parts suppliers: output up 32.67%, though from a slower base.
- Refiners: petroleum products up 12.73%.
Who may face pressure
- Pharmaceutical companies: output down 12.25%.
- Steel mills and builders’ suppliers: iron and steel down 11.77%.
- Food processors and fertiliser makers: down 9.43% and 7.81%.
- Spinners and weavers: textiles down 4.08% in the quarter.
What to watch
- October LSM data: the next PBS release will be the first reading for the second quarter.
- Fuel and power costs: daily fuel pricing and Nepra’s pending tariff decisions feed straight into factory costs.
- Textile orders: whether cotton yarn’s September rise (+4.68%) spreads to the wider sector.
Sources
- Dawn, Big industry output rises 2.07 per cent, 20 Nov 2026
- Dawn, Equities stage mild recovery on value buying, 20 Nov 2026
This is analysis, not investment advice. Figures are as of 20 November 2026.


Leave a Reply