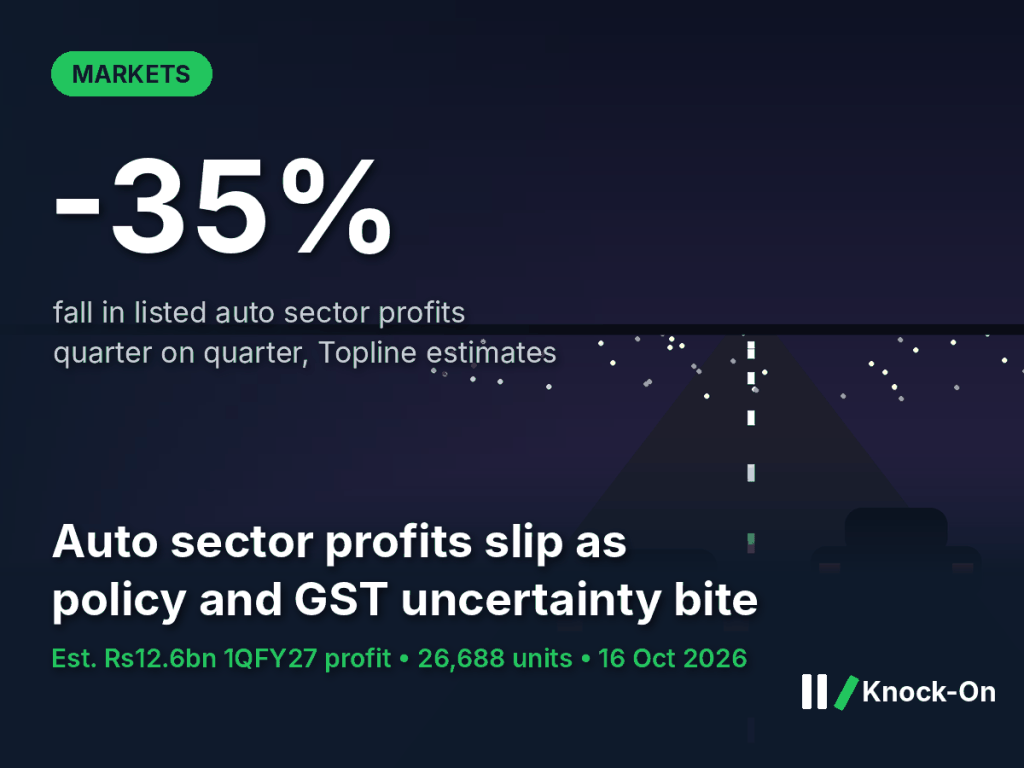
Auto sector profits at Pakistan’s listed carmakers are expected to fall 35% from the previous quarter to about Rs12.6bn in July-September, the first quarter of the 2026-27 fiscal year, according to estimates from Topline Research reported by Business Recorder. The drop comes even though the sector sold 30% more vehicles than a year earlier and earnings are roughly flat year on year. The forecast points to a squeeze from tax changes on hybrid cars, the end of one-off gains, and uncertainty over the government’s next auto policy. Companies are due to report their results in the coming weeks.
The short version
- Topline estimates listed auto earnings of Rs12.6bn for 1QFY27, down 35% quarter on quarter and up 1% year on year.
- Volumes were 26,688 units, up 30% on last year but down 16% on the previous quarter.
- The sector’s gross margin is estimated at 16.4%, against 19.5% a year earlier.
- Indus Motor is the exception, with profit per share forecast up 13% on the quarter.
What happened
In a preview of results, Topline Research projected combined net sales for the listed carmakers of Rs179bn, up 39% year on year but 10% lower than in April-June. It expects the effective tax rate to rise to about 37%, from 34.8% in the previous quarter, and other income to fall 33% to Rs5.3bn because one-off gains from the SIDC settlement will not be repeated. Topline cited “uncertainty over the auto policy” and delays in clarity on sales tax for hybrid and plug-in hybrid vehicles as reasons for the weaker quarter.
Auto sector profits are back to last year’s level after a strong spring
Combined earnings of listed carmakers, Rs bn, by fiscal quarter
The picture differs by company. Indus Motor is forecast to earn Rs87.6 a share, up 2% on last year and 13% on the previous quarter, on sales of 13,261 units. Topline expects its gross margin to improve to 13% from 10.3% and a cash dividend of Rs53 a share. Honda Atlas Cars is forecast to earn Rs5.8 a share, up 11% year on year but down 67% on the quarter, mainly because of lower other income and a normal tax rate. Sazgar Engineering is absorbing a sales tax increase on its hybrid models, which the report says is the main reason for the lower sector margin.
Why it matters
Carmakers sit at the centre of a long supply chain of parts makers, dealers, banks and insurers. Higher sales with thinner auto sector profits suggest companies are holding back price increases or absorbing tax costs to protect demand, a strategy that only works for so long. Our earlier look at Pakistan car sales in the first quarter showed September already slowing as buyers waited for the auto policy.
Indus Motor kept growing its sales
Indus Motor vehicle volumes, units per quarter
The knock-on effects
First order: weaker auto sector profits and payouts
Lower quarterly earnings at most carmakers could mean smaller interim payouts, although Topline still expects Indus Motor to pay out about 60% of its profit. Shareholders will watch whether results match the forecasts.
Second order: hybrid pricing
If the higher sales tax on hybrids stays and companies stop absorbing it, buyers could see price increases on hybrid models. That would test demand at a time when daily petrol pricing is making fuel-efficient cars more attractive.
Third order: the parts chain
Vendors that supply carmakers depend on steady production plans. A quarter-on-quarter fall of 16% in volumes, if it continues, would reach parts makers, logistics firms and auto financing through lower orders.
Who could benefit
- Indus Motor, forecast to grow profit and margin while peers slip.
- Car buyers, for now, while some makers absorb tax increases.
Who may face pressure
- Hybrid makers such as Sazgar, which is absorbing the higher sales tax.
- Honda Atlas Cars, whose quarterly earnings are forecast down 67% as one-off gains fade.
- Parts suppliers if lower quarterly volumes persist.
What to watch
- Actual 1QFY27 results from listed carmakers on the PSX over the coming weeks.
- The government’s new auto policy and any decision on sales tax for hybrid vehicles.
- PAMA’s October sales data, due in early November.
Sources
- Business Recorder, 1QFY27: Auto sector profits seen falling 35pc QoQ, 16 Oct 2026
This is analysis, not investment advice. Figures are as of 16 Oct 2026; earnings figures are forecasts by Topline Research.

Leave a Reply