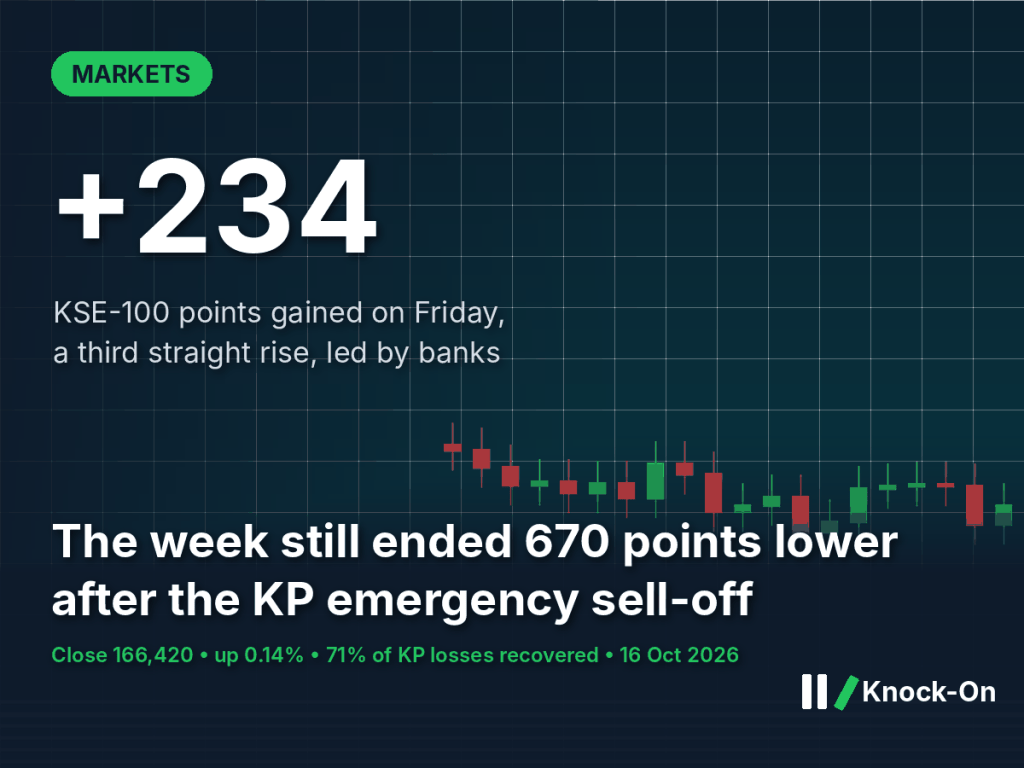
The KSE-100 today closed at 166,419.71, up 233.55 points or 0.14%, its third gain in a row. Banks and technology shares did most of the lifting, while cement and oil exploration stocks held the index back. The rally has now recovered most of the ground lost after emergency rule was imposed in Khyber Pakhtunkhwa, but the benchmark still ended the week about 670 points below last Friday’s close.
The short version
- The KSE-100 rose 233.55 points to 166,419.71, after trading between 165,956.51 and 166,708.36.
- Commercial banks added 95.67 points and technology 60.94; cement took off 54.27 and oil exploration 52.96.
- For the week the index fell 669.56 points (0.40%), after Monday’s 1,965-point drop.
- Trading thinned: market-wide volume fell to 396.90 million shares from 517.20 million on Thursday.
What happened
The index opened firmly and was up 346.70 points at 166,532.86 when trading paused for Friday prayers, Business Recorder reported, with buying in banks, cement, autos, oil marketing, power and refineries. Part of that gain faded in the afternoon. At the close, Systems Ltd (+82.08 points), UBL (+57.35), MCB (+50.89), Bank AL Habib (+41.80) and Engro Fertilizers (+37.18) were the biggest contributors, according to Mettis Global. OGDC (-72.27), Lucky Cement (-53.14), Meezan Bank (-42.10), PTCL (-30.80) and Engro Holdings (-24.41) weighed most.
Breadth was narrow: 54 index stocks rose and 45 fell. Across the whole market, more shares fell (254) than rose (211), and traded value dropped by Rs4.88 billion to Rs18.68 billion. Thursday’s session had been far busier, with the KSE-100 up 768.66 points on volume of about 518 million shares.
Three gains in a row have not yet undone Monday’s fall
KSE-100 daily change, index points, 12–16 October 2026
Why it matters
The KSE-100 today sits about 1,643 points above Tuesday’s low of 164,776.44, which by Knock-On’s calculation means it has won back about 71% of the fall that followed governor’s rule in KP, now approved by Parliament. That suggests investors see the political shock as contained for now. But the slowing pace and thinner volumes show buyers are cautious near last week’s levels. The index is also down 7.70% in the fiscal year to date and 4.39% since January, Mettis Global reported, so this is a recovery within a weak year.
The knock-on effects
First order: banks lead as rates stay high
Banks were again the largest support. With the SBP policy rate at 11.5% and T-bill yields up to 12.5%, lenders’ earnings on government paper remain strong, which keeps them attractive to investors.
Second order: oil stocks track crude, not the rally
OGDC was the biggest drag as Brent eased towards $105 on reports the US may relax some tanker sanctions. Exploration shares tend to move with crude, so the Houthi attacks on Saudi Arabia and Pakistan’s oil import bill cut both ways for the market: good for producers, bad for the economy.
Third order: companies watching for a funding window
A steadier market helps companies weighing share sales or rights issues. If the index can hold above 166,000 and retake last week’s level, the case for raising equity improves; another shock would push those plans back.
Who could benefit
- Banks, which led Friday’s gains on strong earnings from high yields.
- Technology companies, with Systems Ltd the single biggest contributor.
- Brokers, if the recovery holds and activity picks up again.
Who may face pressure
- Cement makers, the weakest sector on Friday.
- Oil exploration companies, exposed to any further easing in crude.
- Investors buying near resistance, if thin volumes signal fading momentum.
What to watch
- Whether the KSE-100 can retake last Friday’s close of 167,089 next week.
- The court hearing on KP’s emergency rule on 20 October.
- Brent crude and further Houthi attacks on Saudi Arabia.
- The SBP monetary policy decision on 26 October.
- The FBR’s extended income tax return deadline of 31 October.
Sources
- Mettis Global, PSX Closing Bell: Little Gains, Longer Streak, 16 October 2026
- Business Recorder, PSX: buying continues. KSE-100 up over 300 points, 16 October 2026
- ARY News, PSX: Stocks close higher as KSE-100 index gains over 700 points, 15 October 2026
- Business Recorder, Selling continues at PSX, KSE-100 Index closes 348 points lower, 13 October 2026
- Mettis Global, PSX Closing Bell: A Shade Lower, 9 October 2026
This is analysis, not investment advice. Figures are as of 16 October 2026.

Leave a Reply