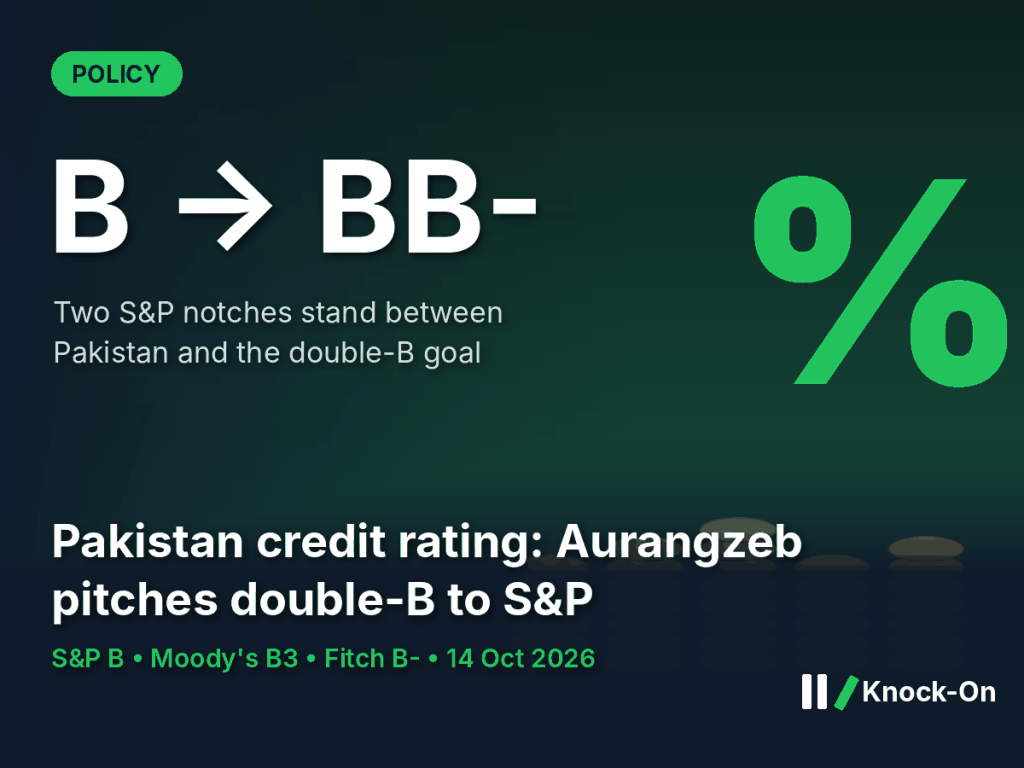
Pakistan’s finance minister has put a new marker on the Pakistan credit rating. Meeting S&P Global Ratings in Bangkok on the sidelines of the World Bank and IMF Annual Meetings, Muhammad Aurangzeb said Pakistan aims to reach the “double-B rating category”, Business Recorder reported on 14 October. S&P rates Pakistan B, so the goal is at least two notches away. For businesses, the rating is not an abstraction: it shapes what the government, banks and large companies pay to borrow abroad.
The short version
- Aurangzeb told S&P that Pakistan’s ambition is a double-B rating; the lowest step in that category, BB-, is two notches above S&P’s current B.
- All three big agencies have Pakistan in single-B: S&P B (July 2026), Moody’s B3 (August 2026) and Fitch B- (affirmed April 2026).
- Pakistan raised $3bn in Eurobonds in September at coupons of 7.50% and 7.90%.
- In the same trip, he discussed US energy imports, Boeing aircraft financing and a trade framework with a US State Department official.
What happened
According to Business Recorder, Aurangzeb briefed S&P on the September bond issue, progress under the IMF programme, better tax collection, higher reserves and lower swap and forward liabilities. He said the agency’s key considerations were policy continuity, reform implementation, a lower interest burden and stronger external buffers. The talks also covered agricultural income tax, energy and food security, and climate resilience.
S&P raised Pakistan to B from B- on 22 July 2026, citing institutional stability and IMF-backed reforms, Profit reported; it was the first B rating since early 2019. Moody’s upgraded Pakistan to B3 from Caa1 on 24 August, Dawn reported, and Fitch affirmed B- with a stable outlook in April. Separately, Aurangzeb told investors at a Citi forum that Pakistan expects growth of 4% or more and plans further Panda bonds, sukuk and a rupee-denominated, dollar-settled international bond.
Double-B would halve the distance to investment grade
Notches below investment grade (BBB- / Baa3), October 2026
Why it matters
Each notch tends to lower the premium investors demand. Pakistan paid 7.50% on $1.75bn of 5.5-year bonds and 7.90% on $1.25bn of 10-year bonds in September, against an order book of nearly $6bn, Business Today reported. A better Pakistan credit rating would also ease the ceiling that applies to banks and companies borrowing abroad. Moody’s pointed to the trend behind its upgrade: interest payments fell to about 35% of government revenue in FY26 from 49% in FY25, and reserves reached about $17bn at end-July. Inflation remains a risk, with the IMF now forecasting 9.9%.
The knock-on effects
First order: cheaper refinancing, if it comes
Moody’s cited IMF estimates that Pakistan needs about $21bn of external financing in FY27 and $30bn in FY28. Even small cuts in borrowing costs on that scale free up money in the budget, which could ease pressure for new taxes on business.
Second order: corporate access to foreign money
Banks and large companies are usually rated no higher than the sovereign. A higher ceiling makes trade finance, project loans and bond issues abroad easier to price. The US talks point the same way: Aurangzeb discussed financing through the US Development Finance Corporation and EXIM Bank, and Boeing aircraft financing, relevant to airlines such as PIA, which is leasing Dreamliners for UK routes.
Third order: politics and security are in the score
S&P has listed domestic and external security risks, and tensions with India and Afghanistan, as rating risks, Profit reported. The emergency in Khyber Pakhtunkhwa, which hit the KSE-100 this week, is the kind of event agencies weigh under policy continuity.
Who could benefit
- The Finance Ministry: lower coupons on future Eurobonds, Panda bonds and sukuk.
- Banks and large corporates: a higher ceiling for foreign borrowing.
- Importers of capital goods: aircraft, energy and project financing backed by US agencies.
Who may face pressure
- Taxpayers: the fiscal discipline agencies reward means continued pressure to widen the tax net, including agricultural income.
- Energy-intensive sectors: higher oil prices are a risk Moody’s flagged to inflation and the external account.
- Bondholders: if the double-B push stalls, today’s single-B pricing may persist.
What to watch
- Fitch’s next review, as it rates Pakistan one notch below S&P.
- The size and timing of the next Panda bond and sukuk issues.
- Progress on the US trade framework agreement and energy imports.
- Reserves against Moody’s projection of about $19bn to $20bn by end-FY27.
Sources
- Business Recorder, Pakistan eyes US energy imports, Boeing aircraft financing, 14 Oct 2026
- Business Recorder, Pakistan expects over 4% growth, to diversify financing with Panda bonds, sukuk, 14 Oct 2026
- Profit, S&P upgrades Pakistan’s sovereign credit rating to B on IMF-backed reforms, 22 Jul 2026
- Dawn, Moody’s lifts Pakistan sovereign rating to B3 from Caa1, 24 Aug 2026
- Pakera, Pakistan credit rating 2026: Moody’s B3, S&P B, Fitch B-, 2026
- Business Today, Pakistan raises $3 billion in landmark Eurobond deal, 4 Sep 2026
This is analysis, not investment advice. Figures are as of 14 October 2026.

Leave a Reply