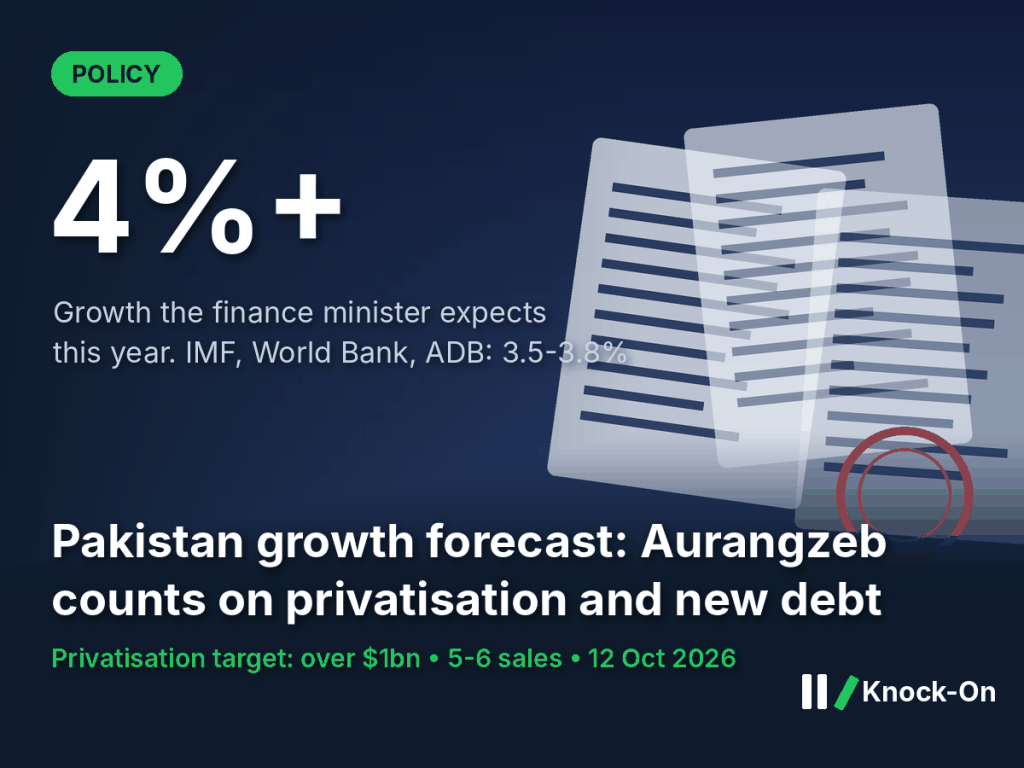
Finance Minister Muhammad Aurangzeb has set out an upbeat Pakistan growth forecast at the IMF and World Bank annual meetings in Bangkok. He told Reuters on Monday that the economy should grow by more than 4% this fiscal year despite high oil prices, and that five or six state-owned entities could be sold this year, raising more than $1 billion. In a separate interview with Bloomberg, he said Pakistan would refinance some short-term external debt into longer maturities over the next two to three years. For businesses, the question is how much of that depends on things that have not yet happened.
Update, 13 Oct 2026, 1:00 pm PKT: The IMF’s October World Economic Outlook, released on Tuesday, keeps its Pakistan growth forecast for 2026-27 at 3.5%, still below the minister’s “north of 4%”, but raises its inflation forecast to 9.9% from 8.4% and sees a current account deficit of about 1% of GDP, according to The Express Tribune. We look at what that means for borrowing costs in our story on the IMF inflation forecast for Pakistan.
The short version
- Mr Aurangzeb expects growth “north of 4%” in 2026-27. The IMF (3.5%, July), the ADB (3.7%, September) and the World Bank (3.8%, October) all forecast less.
- Five or six entities could be privatised this fiscal year for more than $1 billion, from a pipeline of about a dozen that includes power distribution companies and airport operations.
- Pakistan plans to refinance short-term external debt over two to three years while keeping total external debt, close to $100 billion, broadly unchanged.
- A proposed $10 billion exchange stabilisation facility with the United States is under negotiation, with no timeframe given.
What happened
Speaking to Reuters on the sidelines of the meetings, which run from 12 to 18 October, Mr Aurangzeb said: “So I’m still quite clear that we should clock north of 4%.” He said Pakistan had secured adequate fuel supplies with no shortages, that agriculture was holding up, and that the government was watching inflation closely because of its knock-on effect on commodity prices.
On privatisation, he said about a dozen entities were in the pipeline, including state-owned power distribution companies and the outsourcing of airport operations, and that five or six could be completed this fiscal year. “We are quite clear that we want the private sector to lead the country,” he said.
In his Bloomberg interview, the minister said Pakistan does not need to cover an external financing gap this year and is “not in a rush” to issue bonds. The aim is to replace and diversify debt and lengthen maturities. The government has mandated an Islamic sukuk and Pakistan’s first dollar-settled, rupee-denominated bond, will seek proposals for its remaining Panda bonds, and may explore tokenising existing Eurobonds.
The government’s growth forecast is above every major lender’s
Forecast real GDP growth for Pakistan, fiscal year 2026-27 (%)
Why it matters
The gap between the official Pakistan growth forecast and the lenders’ numbers is less than one percentage point, but it matters for planning. Revenue targets, import demand and company sales budgets all rest on a growth assumption. Last week’s IMF staff-level agreement, which could release about $1.21 billion, came with a requirement to keep monetary policy tight, so faster growth would have to come from investment and exports rather than cheaper credit. Reuters notes that Pakistan remains highly exposed to a prolonged Middle East conflict through Gulf energy imports, remittances and regional financing, a risk that has grown as Houthi attacks on Saudi airports disrupt travel.
The knock-on effects
First order: privatisation becomes the test
Reuters describes privatisation as a key test of reform credibility with the IMF, and officials have warned that failing to sell loss-making state firms could renew pressure on public finances. Selling power distribution companies would move some of the power sector’s losses off the state’s books; delays would leave them there.
Second order: longer debt, fewer rollover scares
Replacing short-term external debt with longer maturities reduces the risk of a funding squeeze each time loans fall due. If it works, that could mean fewer episodes of pressure on reserves and the rupee.
Third order: whether growth reaches consumers
Even 4% growth is modest for a population of about 255 million. The World Bank has already warned that poverty is rising, which weighs on demand for everyday goods. If growth lands nearer the lenders’ forecasts, consumer-facing businesses should not expect a quick recovery in volumes.
Who could benefit
- Private investors and bidders for power distribution companies and airport operations, if transactions go ahead.
- Banks, advisers and law firms working on privatisations, sukuk and new bond issues.
- Importers and exporters, if longer debt maturities reduce rollover risk and support a steadier rupee.
Who may face pressure
- Employees and suppliers of state entities that are restructured or sold.
- Businesses whose plans assume growth above 4%, if the lower forecasts prove right.
- Energy-intensive firms, while oil prices stay high.
What to watch
- 12 to 18 October: the IMF and World Bank annual meetings, and any updated IMF forecast for Pakistan.
- The IMF Executive Board date for last week’s staff-level agreement.
- A timetable for the first privatisation transactions and for the sukuk and rupee-denominated bond.
- Progress on the proposed $10 billion US facility; no timeframe has been given.
Sources
- Business Recorder (Reuters), Pakistan sees growth above 4%, looks to raise more than $1 billion from privatisation, 12 October 2026
- Business Recorder, Pakistan to refinance short-term external debt to reduce rollover risks: Aurangzeb, 12 October 2026
- ARY News, World Bank projects 3.8% growth rate in Pakistan during FY2026-27, 7 October 2026
- ARY News, ADB projects Pakistan’s FY2027 growth at 3.7%, 23 September 2026
- ProPakistani, Pakistan Will Miss Its FY27 Growth Target: IMF, 9 July 2026
- The Express Tribune, IMF raises inflation forecast to 9.9%, 13 October 2026
This is analysis, not investment advice. Figures are as of 12 October 2026.


Leave a Reply