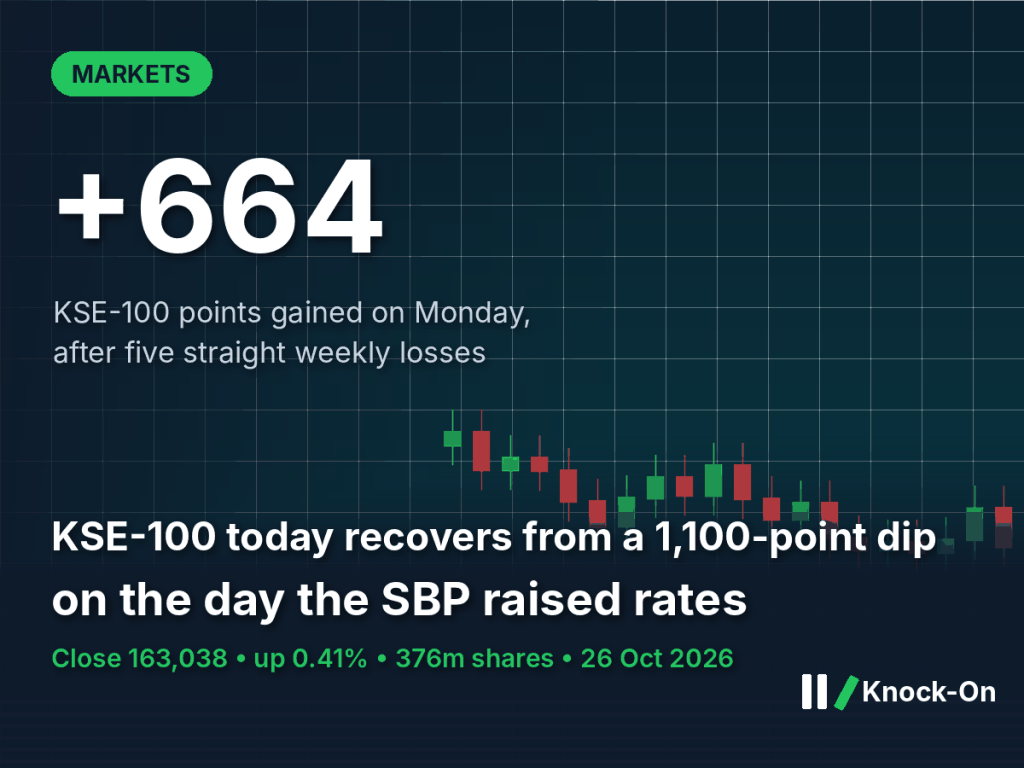
KSE-100 today ended higher after a volatile session. The Pakistan Stock Exchange’s benchmark index closed on Monday, 26 October, at 163,038.46, up 663.59 points or 0.41%, according to Business Recorder. It had fallen more than 1,100 points in early trade as investors waited for the State Bank’s rate decision, then recovered on late buying. The rise breaks a run of five straight weekly losses, but it recovers only a small part of the ground lost last week.
The short version
- The KSE-100 closed at 163,038.46, up 663.59 points (0.41%).
- It traded between 161,250.06 and 163,477.08 during the day.
- The SBP raised its policy rate by 50 basis points to 12% the same day.
- Last week the index lost 4,044.84 points (2.4%), its fifth weekly loss in a row.
What happened
The index opened lower and slid to 161,250.06 by midday, about 1,125 points below Friday’s close of 162,374.84, as selling hit automobile assemblers, cement, commercial banks, refineries and oil and gas companies, Profit and The Express Tribune reported. Analysts had expected a 50 basis point hike from the Monetary Policy Committee. Later in the session buyers returned, and the KSE-100 today touched a high of 163,477.08 before settling at 163,038.46.
According to Bloom Pakistan, about 376 million shares worth roughly Rs16.2bn changed hands. UBL, Engro Holdings, Lucky Cement, OGDC and Mari together added about 718 points, while Meezan Bank, Engro Fertilizers and Fauji Fertilizer took about 317 points off the index.
Monday’s gain recovers about a sixth of last week’s loss
KSE-100 moves, index points, week to 23 Oct and session of 26 Oct 2026
Why it matters
The rate decision removed one source of uncertainty. The SBP interest rate hike to 12% was the outcome most analysts expected, so the market had partly priced it in during five weeks of selling. Still, after five weekly losses in a row, the KSE-100 today is lower than it was five weeks ago, and the drivers of that slide have not gone away. Brent slipped 1.6% to $114.88 on reports that Qatari mediators were in Tehran, Business Recorder said, but that is still well above the $100 Brent assumption behind Topline’s inflation forecast. Last week’s losses, covered in Knock-On’s report on Friday’s 1,549-point fall, were driven by the same oil and rate worries.
The knock-on effects
First order: KSE-100 today shows relief, not a turn
A 0.41% gain after a 2.4% weekly loss is a pause in selling. Whether it becomes a recovery depends on oil and on how quickly higher rates feed through to company earnings.
Second order: higher rates reprice stocks
A 12% policy rate raises the return available on bank deposits and government paper, which competes with equities for savers’ money. Indebted companies in cement, autos and steel face higher finance costs.
Third order: oil and Gulf talks set the tone
Progress in the Makkah pact Iran talks could ease oil prices and inflation fears; a setback would add to pressure on the index.
Who could benefit
- Banks: UBL was among Monday’s top contributors; higher rates can widen lending margins.
- Oil and gas producers: OGDC and Mari gained, with crude prices still above $110.
- Brokers: volume of about 376 million shares points to active trading.
Who may face pressure
- Fertiliser stocks: Engro Fertilizers and Fauji Fertilizer were among the biggest drags.
- Leveraged sectors: autos and cement were among the early sell-off.
- Companies planning to raise capital: weak valuations make listings and rights issues harder.
What to watch
- Tuesday, 27 October: the market’s first full session after the rate decision.
- Brent crude: whether it holds near $115 as Gulf talks continue.
- Results season: quarterly earnings, especially from banks and cement makers.
- Early November: October CPI inflation data.
Sources
- Business Recorder, PSX: volatility at bourse, KSE-100 settles with over 650 points gain, 26 Oct 2026
- Bloom Pakistan, PSX rebounds by 664 points after five consecutive weeks of losses, 26 Oct 2026
- Profit, PSX falls ahead of SBP policy decision, 26 Oct 2026
- The Express Tribune, PSX sheds 715 points as investors brace for policy rate decision, 26 Oct 2026
- Business Recorder, SBP hikes policy rate to 12% on inflation, energy price concerns, 26 Oct 2026
This is analysis, not investment advice. Figures are as of 26 October 2026.

Leave a Reply