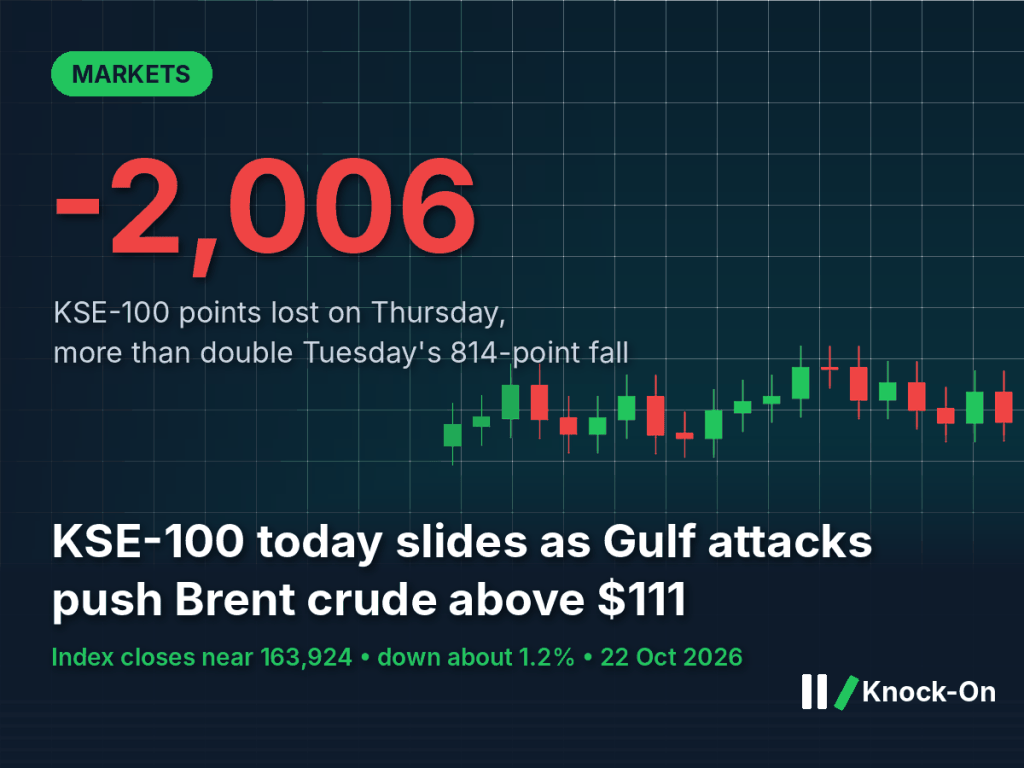
The KSE-100 today fell 2,006 points to close at about 163,924 on Thursday 22 October, Capital News Point reported, more than wiping out Wednesday’s 779-point rebound. The index opened about 250 points higher at 166,180 before selling took over. The trigger was outside Pakistan: new attacks in the Gulf pushed Brent crude to $111.64 a barrel, near a five-month high, and Business Recorder linked the fall to the escalating Middle East conflict. For businesses, the message is that oil, not local news, is setting the market’s direction this week.
The short version
- The KSE-100 closed at about 163,924, down 2,006 points or about 1.21% from 165,930.99 (Knock-On calculation).
- Since last Friday’s close of 166,419.71, the index has lost about 2,496 points, or 1.5% (Knock-On calculation).
- Oil and gas producers, oil marketing companies, power, cement, carmakers and refiners were under pressure by midday.
- The rupee barely moved, closing at 276.85 to the dollar.
What happened
By midday the index had already fallen 1,422 points to 164,509, with a session low of 164,186.90, The Express Tribune reported. It said index-heavy stocks trading lower included OGDC, PPL, Mari, Hubco, PSO, HBL and UBL, and that the selling erased the previous day’s gains, which had been helped by hopes for US-Iran diplomacy and by the draft auto policy. Selling then intensified into the close. The KSE-100 today move is the largest daily swing in the index this week, as the chart shows.
Thursday’s fall was the biggest move of the week
KSE-100 daily change in index points, 19–22 October 2026
Why it matters
Brent rose $2.82 to $111.64 on Thursday morning, Business Recorder reported, after Houthi strikes on an airport in Dammam and a drone attack near Saudi Aramco’s Shaybah oilfield. Iran’s Revolutionary Guards Navy also said it had hit vessels in the northern Gulf and warned the US of a wider response; those are Iranian claims and were not independently confirmed. For Pakistan, which imports most of its fuel, dearer crude feeds straight into the import bill, inflation and the price at the pump. It also lands just before the State Bank’s interest rate decision on 26 October, and on the same day the IMF said Pakistan may need tighter monetary policy if the regional crisis persists.
The knock-on effects
First order: KSE-100 today hits investor portfolios across sectors
The fall was broad, taking in banks, cement and carmakers as well as energy stocks. Equity funds that recovered on Wednesday are now lower for the week, and companies that report results soon will do so against a weaker market backdrop.
Second order: higher oil raises costs and rate risk
Crude above $110 raises costs for transporters, factories and power producers that burn fuel, and keeps pressure on the petroleum levy debate ahead of Friday’s talks. If inflation expectations rise, the case for the SBP to hold or raise rates grows, which matters for any business that borrows.
Third order: volatility makes planning harder
Four sessions this week have swung between gains and losses of several hundred to 2,000 points. Companies weighing share sales, rights issues or listings face a harder time pricing them while the market reacts day by day to news from the Gulf.
Who could benefit
- Long-term buyers: lower prices may appeal to investors with cash and a longer horizon.
- Oil and gas producers’ revenues: higher crude lifts the value of their output, even though their shares fell today.
- Brokers: volatile sessions tend to bring more trading.
Who may face pressure
- Fuel-heavy businesses: transport, power and industry face higher costs if crude stays above $110.
- Borrowers: an oil-driven inflation scare could keep interest rates high.
- Companies planning to raise equity: sharp daily swings complicate pricing.
What to watch
- Friday 23 October: talks on the petroleum levy, and the next PSX session.
- 26 October: the SBP monetary policy decision.
- Brent crude: any further attacks on Gulf shipping or Saudi oil sites.
- The rupee: so far steady near 276.85 to the dollar.
Sources
- Capital News Point, Pakistan Stock Exchange Plunges 2,006 Points as KSE-100 Closes Lower, 22 October 2026
- Business Recorder, PSX: KSE-100 down over 2,000 points amid escalating ME conflict, 22 October 2026
- The Express Tribune, PSX plunges over 1,400 points as selling pressure mounts, 22 October 2026
- Business Recorder, Oil jumps $2 on escalating Middle East tension, 22 October 2026
- Business Recorder, IMF flags rising inflation risks for Pakistan amid Middle East conflict, 22 October 2026
- Business Recorder, Pakistan rupee records gain against US dollar, 22 October 2026
- Business Recorder, Stocks rebound as KSE-100 closes with 779 points gain, 21 October 2026
- Knock-On, KSE-100 today regained 779 points, almost all of Tuesday’s loss, 21 October 2026
This is analysis, not investment advice. Figures are as of 22 October 2026.

Leave a Reply