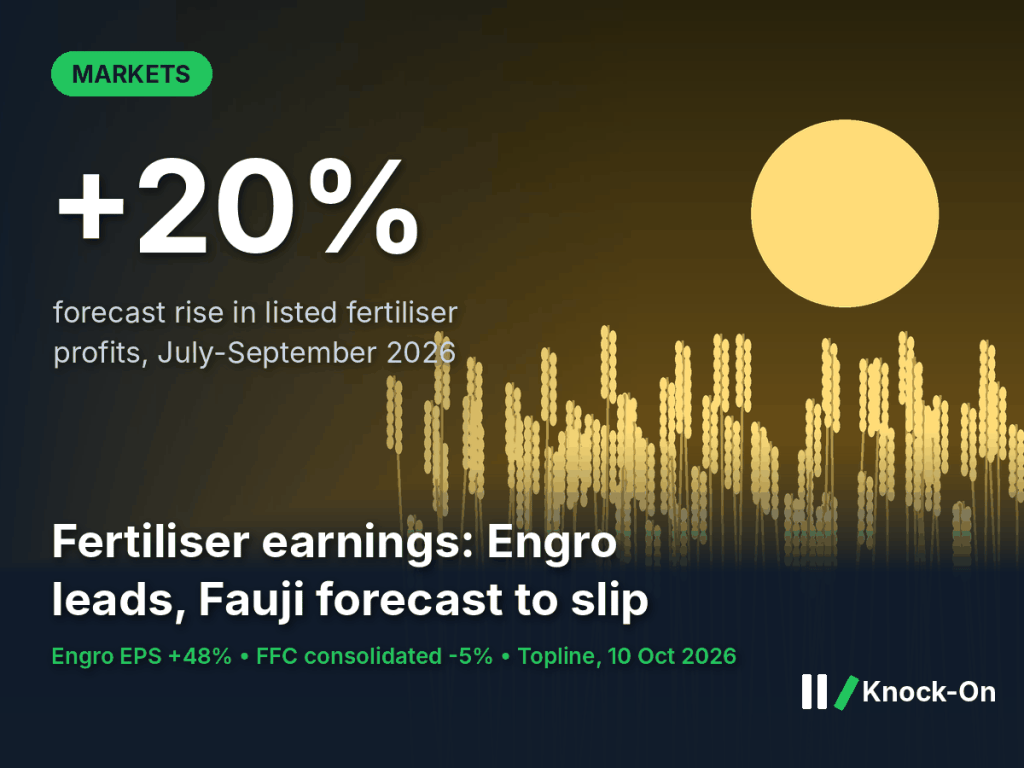
Pakistan’s listed fertiliser companies are expected to report a 20% year-on-year rise in profits for July-September 2026, according to a forecast by brokerage Topline Research. The growth is uneven: Engro Fertilizers is forecast to lift earnings per share by nearly half, while Fauji Fertilizer’s consolidated earnings are expected to dip. Results season starts in the coming weeks.
Update, 13 Oct 2026, 9:00 pm PKT: A new risk for the sector’s winter output: the Petroleum Division’s draft winter gas plan says the three LNG-fed plants, Fauji Fertilizer Bin Qasim, Fatima Fertilizer and Agritech, could be closed in December and January, cutting about 109,000 tonnes of urea a month, though no final decision has been taken (Business Recorder). Read our analysis of the gas load shedding plan for Pakistan this winter.
The short version
- Topline forecasts listed fertiliser profits up 20% year-on-year and 7% on the previous quarter, on sales of Rs200.5 billion.
- Drivers: higher urea volumes, better realised prices held without discounts, and dividend income.
- Engro Fertilizers’ EPS is forecast at Rs6.45, up 48%; FFC’s consolidated EPS at Rs16.12, down 5%.
- DAP sales fell 20% year-on-year, and phosphoric acid costs are reported up 29%.
What happened
In a preview reported by Business Recorder on 10 October, Topline Research projected combined sector turnover of Rs200.5 billion for the third calendar quarter, up 10% year-on-year and 46% on the quarter. The gross margin is forecast at 33.09%, up from 31.35% a year earlier. Finance costs are projected to rise 44% to Rs4 billion, mainly because Engro Fertilizers borrowed while carrying high inventory.
Volumes explain much of the split. Industry urea sales reached 1.9 million tonnes in the quarter, up 2% year-on-year and 28% on the quarter. FFC’s urea sales fell 9% to 756,000 tonnes, while the rest of the industry grew 11%. Engro is forecast to have sold 711,000 tonnes of urea, with revenue up 40% to Rs76.4 billion.
Engro is forecast to drive the sector’s profit growth
Forecast change in profit / earnings per share, July-September 2026 vs a year earlier (%)
Why it matters
Fertiliser is one of the PSX’s heaviest sectors and a large dividend payer, so its results shape market sentiment early in the earnings season. Topline expects Engro to pay Rs6 a share and FFC Rs11.50 a share. The numbers also say something about farming: urea demand held up, with January-September sales up 5% to 4.4 million tonnes, but DAP sales fell 5% over the same period, suggesting farmers are spending less on phosphate.
The knock-on effects
First order: strong prices, steady volumes
Topline attributes the margin gain to higher prices holding without discounts. For manufacturers, that means wider margins; for farmers, it means the higher price is being paid in full.
Second order: a phosphate squeeze
Phosphoric acid, a key DAP input, is reported up 29%, and DAP sales fell 20% year-on-year in the quarter. If farmers continue to cut phosphate use because of price, it could affect crop yields for the coming wheat season.
Third order: borrowing costs bite
The 44% jump in finance costs shows the price of holding stock at current interest rates. With the IMF programme keeping monetary policy tight, and wholesale prices rising faster than shop prices, companies carrying inventory will keep feeling it.
Who could benefit
- Engro Fertilizers, forecast to gain urea market share and lift DAP sales 168%.
- Income-focused shareholders, if the forecast dividends are confirmed.
- The tax collector: sector tax expense is forecast at Rs19.2 billion, up 14%.
Who may face pressure
- Fauji Fertilizer, with urea sales down 9% and DAP sales down 22%.
- Farmers paying full price for urea and more for DAP.
- DAP importers and sellers facing higher input costs and weaker demand.
What to watch
- Actual quarterly results from Engro Fertilizers and FFC, due in the coming weeks, against these forecasts.
- Whether the declared dividends match the forecast Rs6 and Rs11.50 a share.
- DAP prices and sales ahead of wheat sowing.
Sources
- Business Recorder, Q3: Fertiliser sector may post 20pc profit growth YoY, 10 October 2026 (citing Topline Research)
This is analysis, not investment advice. Figures are forecasts as of 10 October 2026.


Leave a Reply