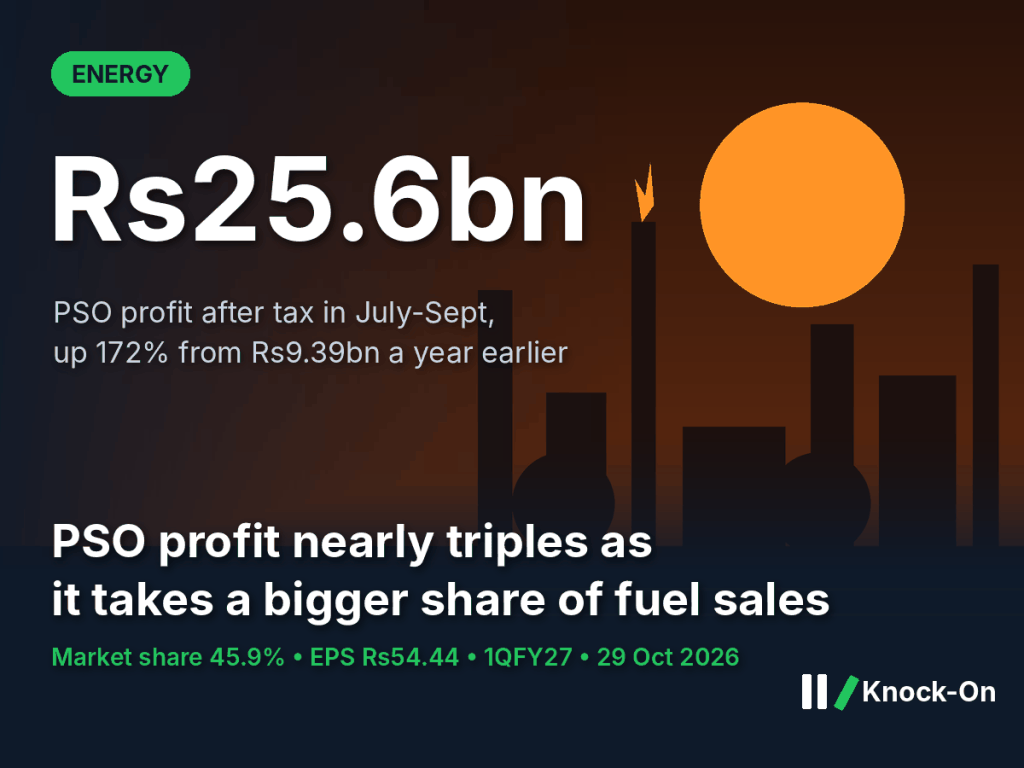
PSO profit rose to Rs25.56bn in the first quarter of the 2026-27 financial year, up 172% from Rs9.39bn a year earlier, Pakistan State Oil said on Thursday, 29 October, Business Recorder reported. The state-owned fuel company grew its petroleum sales by 17.8% in July–September, more than twice the 7.1% growth of the whole market, in a quarter marked by supply disruptions. PSO was among the index-heavy stocks trading higher on a day when the KSE-100 rose for a fourth session.
The short version
- PSO’s standalone profit after tax was Rs25.56bn in July–September 2026, up 172%; earnings per share were Rs54.44, against Rs20 a year earlier.
- Including Pakistan Refinery Limited, consolidated profit was Rs29.42bn (EPS Rs62.66).
- Its share of the fuel market rose 4.2 percentage points to 45.9%.
- PSO sold 12.8% more diesel even though national diesel demand contracted.
What happened
According to the company’s statement, reported by Business Recorder, the jump in PSO profit came from higher sales volumes and a better product mix. Petrol (motor gasoline) sales rose 23.2% to 968,000 tonnes and diesel sales rose 12.8% to 759,000 tonnes. Jet fuel sales rose 15.5%, and PSO supplied 99.6% of Pakistan’s Jet A-1 market. Lubricant sales rose 17.4% to 9,970 tonnes.
To keep supply going, PSO imported 16 cargoes of petroleum products totalling 756,000 tonnes and lifted 1.019 million tonnes of petrol and diesel from local refineries. After the quarter ended, it signed a government-to-government sale and purchase agreement with Oman’s OQ Trading. “We are strengthening our supply chain by broadening sourcing options,” chief executive Jawwad Ahmed Cheema said.
PSO outgrew the fuel market in every product line
Sales growth, % year on year, July–September 2026
Why it matters
PSO profit matters beyond one company. PSO sells almost half of Pakistan’s fuel and imported 16 cargoes in the quarter, so its results show how fuel supply held up in a quarter the company said was marked by supply disruptions, while Gulf attacks pushed oil higher. Growing 17.8% in a market that grew 7.1% means PSO took sales from rival oil marketing companies; its 4.2-point share gain is the clearest sign of that. The fact that national diesel demand contracted is a warning sign for freight and industry, which use most diesel. Knock-On has tracked the cost side in its stories on the diesel price in Pakistan and the oil price forecast for Pakistan.
The knock-on effects
First order: a stronger PSO profit lifts the energy index
PSO is one of the heavier stocks in the KSE-100 and was among the index names trading higher on Thursday, The Express Tribune reported. Strong results from large companies have been a main support for the market’s four-day rally, covered in KSE-100 today.
Second order: supply security shifts to state channels
In a disrupted market, buyers such as transporters, airlines and factories tend to favour the supplier with the most secure cargoes. The new deal with Oman’s OQ Trading adds a government-to-government source outside the most exposed Gulf routes, though its volumes and prices were not disclosed.
Third order: weaker diesel demand points to slower activity
Diesel use is a rough gauge of trucking, farming and industrial activity. A national contraction, at a time of high fuel prices, suggests businesses are cutting back on transport, which could show up later in freight volumes and growth data.
Who could benefit
- PSO shareholders, including the government: earnings per share rose to Rs54.44 from Rs20.
- Pakistan Refinery Limited: PSO’s subsidiary is part of the Rs29.42bn consolidated profit.
- Airlines: PSO supplied 99.6% of Jet A-1 fuel, giving steady supply through the disruption.
Who may face pressure
- Rival oil marketing companies: they shared a smaller part of the market as PSO’s share rose to 45.9%.
- Freight and logistics firms: falling national diesel demand points to weaker business.
- Fuel-heavy businesses: pump prices remain tied to Gulf oil prices above $110 a barrel.
What to watch
- Sunday, 1 November: the OPEC+ meeting on December output, which will shape import costs.
- Coming weeks: results from other oil marketing companies, to see how much share they lost.
- Oman deal: any disclosure of volumes, prices and first cargoes under the OQ Trading agreement.
- Winter: how PSO manages Pakistan’s long-term LNG supply portfolio during peak gas demand.
Sources
- Business Recorder, PSO profit jump 172% to Rs25.6bn in 1QFY27 despite supply disruptions, 29 Oct 2026
- The Express Tribune, KSE-100 index gains 1,136 points in intraday trading amid sustained buying interest, 29 Oct 2026
- Business Recorder, Rupee extends gain against US dollar, 29 Oct 2026
This is analysis, not investment advice. Figures are as of 29 October 2026.

Leave a Reply